Debt Consolidation in 2026: Reduce Payments by 25% with New Loan Options
Anúncios
Managing multiple financial obligations can feel like a never-ending cycle, but a wave of fresh financial restructuring tools is changing the game. Exploring your options for Debt Consolidation in 2026 could be the key to slashing your monthly liabilities by up to a quarter.
Lenders are introducing highly competitive refinancing packages and updated credit criteria to help consumers streamline their liabilities. This shifting economic landscape makes it the ideal moment to merge high-interest balances into a single, much more manageable payment.
Understanding these updated personal finance programs is crucial for taking back control of your budget this year. Here is a clear breakdown of how these strategic refinancing solutions work and how you can leverage them to achieve lasting financial relief.
Understanding the Evolving Landscape of Debt Consolidation in 2026
The financial environment in 2026 presents unique challenges and opportunities for consumers burdened by multiple debts. Inflationary pressures and fluctuating interest rates have spurred lenders to introduce more flexible and competitive debt consolidation products.
These new offerings are specifically designed to address the current economic climate, providing tailored solutions.
Anúncios
Analysts from major financial institutions confirm a noticeable shift in lending strategies, prioritizing long-term financial stability for borrowers. This includes expanded eligibility criteria and more favorable terms for those seeking to combine high-interest debts.
The goal is to make debt management more accessible and effective for a wider demographic.
The push for innovative loan options stems from a collective effort within the financial industry to support economic recovery and consumer well-being.
This proactive approach aims to mitigate the adverse effects of accumulating debt, offering a lifeline to individuals and families struggling with their monthly payments.
Key Drivers Behind New Loan Options
Several factors are converging to shape the new landscape of Debt Consolidation in 2026. Economic forecasts indicate a continued need for consumer financial relief, prompting banks and credit unions to innovate.
Regulatory adjustments are also playing a role, encouraging more transparent and consumer-friendly lending practices.
Technological advancements are streamlining the application and approval processes for consolidation loans. Fintech companies are at the forefront, leveraging AI and data analytics to offer personalized rates and terms.
Anúncios
This digital transformation is making it easier and faster for consumers to access the funds they need.
- Economic downturns and inflation necessitate financial relief.
- Regulatory changes promote fairer lending practices.
- Technological innovation simplifies loan applications and approvals.
Impact of Interest Rate Fluctuations
Interest rate movements are a critical component influencing the attractiveness of new debt consolidation options. As central banks adjust their monetary policies, lenders recalibrate their offerings to remain competitive.
Consumers can benefit from locking in lower fixed rates, protecting themselves from future increases.
The current projections suggest a period where securing a consolidated loan could be particularly advantageous, especially for those with variable-rate debts. This strategic move can provide predictability in monthly payments, a significant relief for budgeting.
Understanding these dynamics is essential for maximizing the benefits of Debt Consolidation in 2026.
Financial advisors emphasize the importance of monitoring market trends closely to identify optimal times for consolidation.
Timing can significantly impact the overall savings achieved through reduced interest charges. Proactive engagement with financial news and expert advice is highly recommended.
New Loan Options: A Pathway to Reduced Payments
The landscape for Debt Consolidation in 2026 is marked by the introduction of several innovative loan products, specifically designed to help consumers reduce their monthly payments.
These new options go beyond traditional personal loans, incorporating features that cater to diverse financial situations. Lenders are focusing on flexibility and affordability to attract borrowers.
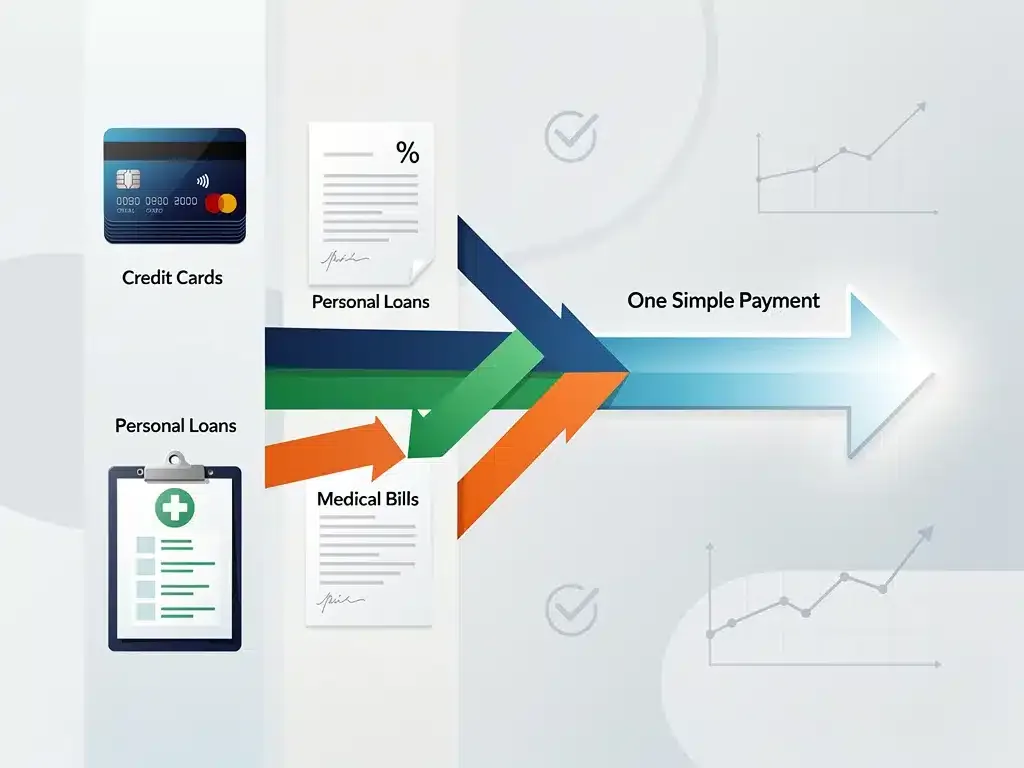
One notable development is the rise of specialized consolidation loans that target specific types of debt, such as medical bills or high-interest credit card balances.
These products often come with lower interest rates and extended repayment periods, making them highly attractive. The goal is to provide a more targeted approach to debt relief.
Furthermore, some financial institutions are exploring hybrid models that combine secured and unsecured loan features, offering a broader range of solutions.
These hybrid options aim to provide better terms for individuals who might not qualify for conventional unsecured loans due to their credit history. This expansion of choices is a key highlight of Debt Consolidation in 2026.
Personal Loans Redefined for 2026
Personal loans remain a cornerstone of debt consolidation, but their structure and accessibility are being redefined for 2026. Lenders are now offering more competitive rates for borrowers with good to excellent credit, coupled with streamlined application processes.
This makes personal loans an even more attractive option for combining various debts into a single, manageable payment.
Beyond traditional banks, online lenders are playing a significant role in this evolution, providing rapid approvals and customizable terms. Their data-driven approach often allows for more personalized interest rates, potentially leading to greater savings.
Consumers are encouraged to compare offers from both traditional and digital platforms to find the best fit.
The flexibility of personal loans in 2026 extends to repayment schedules, with options for longer terms that can significantly lower monthly outlays.
While longer terms might mean more interest paid over time, the immediate relief of reduced payments can be a crucial factor for many. This adaptability is central to the appeal of Debt Consolidation in 2026.
Balance Transfer Credit Cards: Strategic Utilization
Balance transfer credit cards continue to be a viable option for Debt Consolidation in 2026, particularly for those with excellent credit.
Many issuers are extending their 0% APR promotional periods, sometimes up to 24 months, offering a substantial window to pay down debt without incurring interest. This can be a powerful tool if managed correctly.
However, it is crucial to understand the terms and conditions, including balance transfer fees and the interest rate after the promotional period expires. Strategic utilization involves a clear plan to pay off the transferred balance before the higher interest rates kick in.
This requires disciplined budgeting and a commitment to accelerated payments.
- Extended 0% APR promotional periods are common.
- Balance transfer fees and post-promotional rates must be considered.
- Disciplined repayment is essential to maximize benefits.
Achieving Up to 25% Reduction in Payments: How It Works
The promise of reducing monthly payments by up to 25% through Debt Consolidation in 2026 is a significant incentive for many consumers.
This substantial reduction is achievable through a combination of lower interest rates, extended repayment terms, and the elimination of multiple fees associated with various individual debts. Understanding the mechanics is key to realizing these savings.
When you consolidate, you replace several high-interest debts, such as credit card balances or older personal loans, with a single new loan at a more favorable interest rate.
This new loan typically has a longer repayment period, which further reduces the amount due each month. The combined effect of lower rates and longer terms is what drives the potential for significant payment reduction.
For instance, an individual with multiple credit cards carrying average interest rates of 18-25% might consolidate into a personal loan with an interest rate of 8-12%.
If the repayment term is also extended from, say, 36 months to 60 months, the monthly payment can drop considerably. This strategic financial maneuver is at the heart of effective Debt Consolidation in 2026.
Leveraging Lower Interest Rates
One of the primary benefits of Debt Consolidation in 2026 is the ability to secure a lower overall interest rate.
High-interest debts, particularly credit cards, can make significant inroads into your budget, with a large portion of your payment going towards interest rather than the principal. A consolidation loan at a much lower rate immediately frees up cash flow.
Lenders are increasingly offering competitive rates to attract qualified borrowers, recognizing the demand for more affordable debt solutions.
By consolidating, you effectively refinance your existing debts under more favorable terms. This directly translates to less money spent on interest over the life of the loan, maximizing the principal repayment.
It is important to shop around and compare offers from various lenders to ensure you are getting the most advantageous interest rate.
Even a percentage point or two difference can lead to substantial savings over the repayment period, contributing significantly to the heralded 25% payment reduction potential.
Extended Repayment Terms and Budgeting
Extending the repayment term is another powerful mechanism for reducing monthly payments through Debt Consolidation in 2026.
While a longer term means you will be paying interest for a longer period, it drastically lowers the immediate financial burden each month. This can be critical for individuals facing tight budgets.
A lower monthly payment provides greater breathing room in your budget, allowing you to allocate funds to other essential expenses or even build an emergency fund.
This financial flexibility can prevent future debt accumulation and foster healthier spending habits. The immediate relief often outweighs the long-term cost for many consumers.
- Longer repayment terms significantly lower monthly obligations.
- Increased budget flexibility helps prevent future debt.
- Careful consideration of long-term interest costs is essential.
Eligibility and Application Process in 2026
Navigating the eligibility requirements and application process for Debt Consolidation in 2026 is crucial for securing the best available options.
While criteria vary by lender, common factors include credit score, debt-to-income ratio, and employment history. Lenders are looking for indicators of financial stability and the ability to repay the new consolidated loan.
Many financial institutions are enhancing their digital application platforms, making the process faster and more user-friendly.
Online applications often provide instant pre-qualification, allowing you to gauge your eligibility and potential interest rates without impacting your credit score. This efficiency is a hallmark of the modern lending environment.
It is advisable to gather all necessary financial documents, such as recent pay stubs, bank statements, and details of all existing debts, before starting the application.
Being prepared can significantly expedite the process and ensure a smooth experience. This proactive approach is key to leveraging Debt Consolidation in 2026 successfully.
Credit Score Considerations
Your credit score plays a pivotal role in determining your eligibility and the interest rate you’ll receive for Debt Consolidation in 2026.
A higher credit score typically translates to more favorable terms, including lower interest rates and better loan amounts. Lenders view a strong credit history as an indicator of responsible financial management.
For those with less-than-perfect credit, options still exist, though they might come with slightly higher interest rates or require a co-signer.
Some lenders specialize in assisting borrowers with fair credit, offering tailored solutions. Improving your credit score even marginally before applying can yield significant benefits.
- Higher credit scores lead to better loan terms.
- Options exist for fair credit, often with higher rates.
- Improving credit before applying is a strategic move.
Required Documentation and Digital Convenience
The documentation requirements for Debt Consolidation in 2026 are becoming increasingly streamlined, especially with the prevalence of digital platforms.
While specific documents may vary, generally you will need proof of identity, income verification, and details of the debts you wish to consolidate. Many online lenders allow for electronic submission of these documents.
The convenience of digital applications means you can often complete the entire process from home, saving time and effort.
This includes uploading documents, signing agreements electronically, and receiving funds directly into your bank account. This digital convenience is transforming how consumers access financial services.
It is always recommended to double-check the specific requirements of each lender you consider. Ensuring all necessary documents are accurate and readily available will prevent delays in the application process.
This attention to detail is vital for a smooth transition to a consolidated debt structure.
Potential Pitfalls and How to Avoid Them
While Debt Consolidation in 2026 offers significant advantages, it’s crucial to be aware of potential pitfalls to ensure a truly beneficial outcome.
Consolidating debt is a powerful financial tool, but it requires discipline and a clear understanding of the terms involved. Rushing into a decision without proper research can lead to unintended consequences.
One common pitfall is falling back into debt after consolidation. If the underlying spending habits that led to the initial debt are not addressed, there’s a risk of accumulating new high-interest debt while still paying off the consolidated loan.
This can leave you in a worse financial position than before.
Another area to watch out for is hidden fees or unfavorable terms. Some lenders might offer attractive headline interest rates but include high origination fees or prepayment penalties.
Always read the fine print and ask for clarification on any terms you don’t fully understand. Transparency is paramount when dealing with Debt Consolidation in 2026.
Addressing Spending Habits
The most critical aspect of successful Debt Consolidation in 2026 is addressing the root causes of debt accumulation, primarily spending habits.
A consolidation loan provides a fresh start, but it is not a magic bullet. Without a change in financial behavior, the relief can be temporary, leading to a cycle of debt.
Developing a strict budget, tracking expenses, and prioritizing savings are essential steps. Consider seeking financial counseling to develop sustainable money management skills.
This proactive approach ensures that the benefits of consolidation are long-lasting and contribute to overall financial health.
- Identify and change underlying spending behaviors.
- Create and adhere to a strict personal budget.
- Consider financial counseling for lasting habit changes.
Beware of Hidden Fees and Unfavorable Terms
When evaluating options for Debt Consolidation in 2026, a thorough review of all fees and terms is non-negotiable. Beyond the interest rate, look for origination fees, application fees, late payment fees, and prepayment penalties.
These can significantly impact the true cost of your loan and diminish the savings you hope to achieve.
Some lenders might offer variable interest rates that can increase over time, potentially eroding your anticipated payment reduction. Fixed-rate loans provide more predictability and are often preferred for consolidation purposes.
Always request a clear breakdown of all costs associated with the loan before committing.
It is also wise to compare the total cost of the consolidated loan, including all fees and interest, against the total cost of your current debts.
This comprehensive comparison will reveal whether the consolidation is truly beneficial in the long run. Informed decision-making prevents costly surprises with Debt Consolidation in 2026.
Expert Advice and Future Outlook
Financial experts widely endorse the strategic use of Debt Consolidation in 2026 as a powerful tool for regaining financial control, especially with the new loan options available.
They emphasize the importance of personalized advice and careful planning to maximize benefits. Consulting with a certified financial advisor can provide tailored strategies based on individual circumstances.
The future outlook for debt consolidation remains positive, with ongoing innovation expected in lending products and services.
As technology continues to advance, we anticipate even more streamlined processes and potentially lower barriers to entry for a broader range of borrowers. This continuous evolution aims to make financial relief more accessible.
Authorities are also exploring additional regulatory frameworks to protect consumers and ensure fair lending practices within the consolidation market.
These measures aim to build trust and confidence in the financial system, encouraging more individuals to explore viable debt solutions. The focus remains on sustainable financial health for all.
The Role of Financial Counselors
Financial counselors play an invaluable role in guiding individuals through the complexities of Debt Consolidation in 2026. They can help assess your current financial situation, identify the most suitable consolidation options, and develop a realistic budget.
Their objective advice can be crucial in making informed decisions and avoiding common pitfalls.
Counselors can also assist in negotiating with creditors or developing debt management plans when consolidation isn’t the best fit.
Their expertise extends beyond just loans, encompassing holistic financial planning that addresses spending habits and long-term goals. Engaging a counselor is a proactive step towards lasting financial stability.
- Counselors provide personalized advice and strategy.
- They assist with budgeting and debt management plans.
- Their expertise covers holistic financial planning.
Anticipated Trends in Debt Consolidation
Looking ahead, several trends are expected to shape Debt Consolidation in 2026 and beyond. The increasing adoption of AI and machine learning in credit assessment will likely lead to more precise risk evaluations and personalized loan offers.
This could benefit borrowers with unique financial profiles who might be overlooked by traditional models.
We also anticipate a greater emphasis on financial literacy and education as part of the consolidation process. Lenders and financial institutions are recognizing the importance of empowering borrowers with the knowledge to maintain long-term financial health.
This educational component will be a significant addition to the debt relief landscape.
The integration of environmental, social, and governance (ESG) factors into lending decisions might also emerge, influencing how loans are structured and offered.
While still nascent, this trend could bring a new dimension to responsible lending and borrowing practices. These evolving dynamics highlight the progressive nature of Debt Consolidation in 2026.
| Key Aspect | Description |
|---|---|
| Payment Reduction | New loan options aim to cut monthly payments by up to 25%. |
| New Loan Types | Specialized and hybrid loans with flexible terms are emerging. |
| Eligibility Factors | Credit score, debt-to-income ratio, and income are key considerations. |
| Avoiding Pitfalls | Address spending habits and scrutinize all fees and terms carefully. |
Frequently Asked Questions About Debt Consolidation in 2026
What are the primary benefits of Debt Consolidation in 2026?▼The main benefits include reducing multiple monthly payments into a single, more manageable one, potentially lowering your overall interest rate, and simplifying your financial life. New loan options in 2026 are specifically designed to maximize these advantages, offering greater flexibility and better terms for eligible borrowers seeking financial relief.
How much can I realistically save on monthly payments?▼Many consumers can realistically expect to reduce their monthly payments by up to 25% or even more, depending on their current interest rates and the terms of their new consolidated loan. This saving is achieved through lower interest rates and potentially longer repayment periods, making debt more affordable and manageable over time.
What factors influence my eligibility for new loan options?▼Eligibility is primarily influenced by your credit score, debt-to-income ratio, and stable employment history. Lenders in 2026 are increasingly considering a broader range of financial indicators, and some new options cater to those with fair credit, though terms may vary. Always check specific lender criteria for the best assessment.
Are there any risks associated with Debt Consolidation in 2026?▼Yes, potential risks include falling back into debt if spending habits are not addressed, and the possibility of paying more interest over a longer repayment term. It is crucial to scrutinize all loan terms, including fees and interest rates, and to commit to responsible financial management to avoid these pitfalls and maximize benefits.
Where can I find reliable advice on consolidating my debt?▼Reliable advice can be found from certified financial advisors, non-profit credit counseling agencies, and reputable financial institutions. These resources can provide personalized guidance, help you assess your options, and assist in developing a comprehensive financial plan. Always seek objective, expert advice to ensure the best outcome for your situation.
Looking Ahead: Navigating Your Financial Future
The insights into Debt Consolidation in 2026 underscore a dynamic financial landscape offering significant opportunities for relief.
The availability of new loan options and the potential to reduce payments by up to 25% present a clear pathway for consumers to achieve greater financial stability. As the year progresses, staying informed about these evolving options will be paramount.
What happens now involves a proactive approach: assessing your current debt, exploring the new consolidation products, and critically evaluating the terms.
The emphasis remains on informed decision-making and responsible financial management to leverage these opportunities effectively. This moment represents a crucial turning point for many seeking debt relief.
KanguruNews.com will continue to monitor developments in Debt Consolidation in 2026, providing timely updates and expert analysis.
We encourage readers to utilize the resources available, including financial counselors and comprehensive loan comparison tools, to secure their financial well-being in this evolving economic climate.