Maximizing Your 401(k) in 2026: New Contribution Limits and Investment Opportunities
Anúncios
Are you making the most of your workplace retirement plan this year? When it comes to Maximizing Your 401(k) in 2026, staying ahead of fresh IRS regulations is the single best way to ensure your long-term nest egg grows as fast as possible.
Recent updates from federal authorities and tax experts have officially unlocked higher baseline caps and expanded catch-up opportunities for older savers.
Navigating these modern guidelines helps you lower your taxable income today while building a more resilient financial future.
Here at KanguruNews.com, we break down exactly what changed, why these adjustments matter for your portfolio, and how to execute your next wealth-building moves. Let’s look at how these newly announced benchmarks can optimize your current investment strategy.
Understanding the 2026 401(k) Contribution Limits
The IRS typically announces adjustments to retirement plan contribution limits annually, reflecting inflation and other economic factors. These changes are vital for individuals and employers to plan their financial strategies effectively.
Anúncios
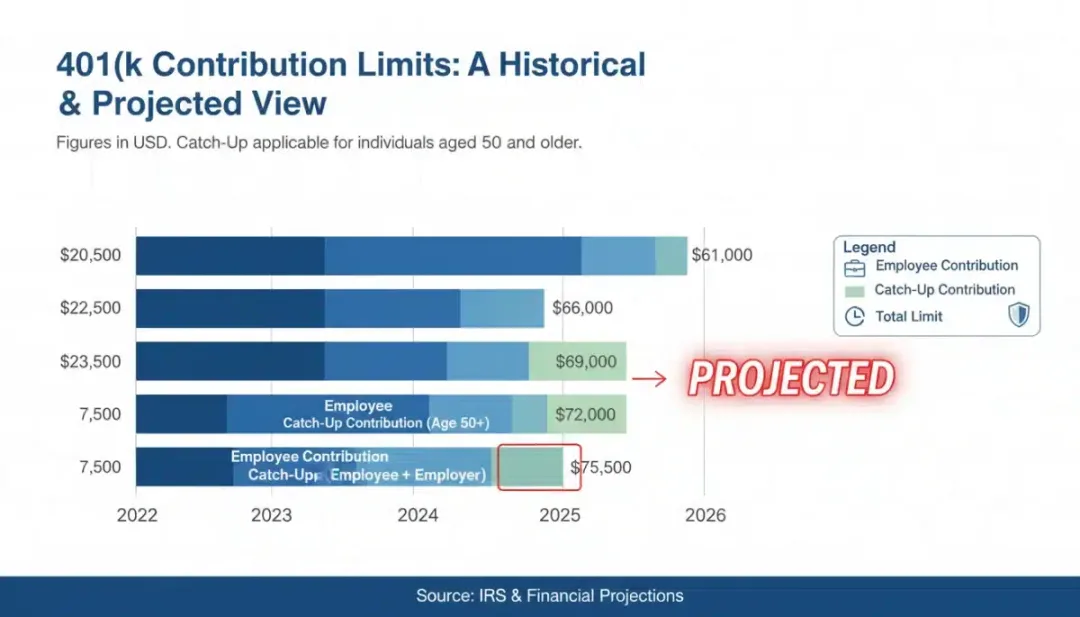
For 2026, projections suggest an upward trend in contribution limits for 401(k) plans, continuing a pattern observed in recent years.
This adjustment aims to help savers keep pace with the rising cost of living and maintain the purchasing power of their future retirement income.
While official figures are usually released later in the year, financial analysts and industry bodies often provide early estimates based on economic forecasts.
These projections allow individuals to begin planning their contributions well in advance, ensuring they are prepared to maximize their retirement savings.
Projected Standard and Catch-Up Limits
The standard elective deferral limit for employees participating in 401(k) plans is expected to see a significant increase for 2026. This means individuals will be able to contribute a larger sum of pre-tax or Roth dollars to their accounts.
For those aged 50 and over, the catch-up contribution limit is also anticipated to rise, providing an additional avenue for older workers to boost their retirement nest egg.
This provision is particularly beneficial for individuals who may have started saving later in their careers or wish to accelerate their savings.
Anúncios
These projected increases underscore the importance of staying informed and adjusting your savings strategy accordingly.
Failing to account for these higher limits could mean missing out on valuable tax-advantaged savings opportunities, hindering your progress towards Maximizing Your 401(k) in 2026.
- Expected increase in the standard 401(k) contribution limit.
- Anticipated higher catch-up contribution limit for individuals 50 and older.
- Opportunity for greater tax-deferred or tax-free growth within your retirement plan.
These adjustments are not merely numerical changes; they represent a continuous effort by policymakers to support long-term financial security for American workers.
The ability to contribute more can significantly impact the compounding growth of retirement funds over time.
Strategic Investment Opportunities within Your 401(k)
Beyond the increased contribution limits, 2026 presents a dynamic landscape of investment opportunities within 401(k) plans. Plan participants should review their portfolio allocations to align with their financial goals and risk tolerance.
Many employer-sponsored plans are expanding their investment menus, offering a wider array of funds, including target-date funds, index funds, and even some alternative investment options. This diversification can help investors tailor their portfolios more precisely.
Consider consulting with a financial advisor to evaluate your current investment mix and explore new options that align with market trends and your personal circumstances. Proactive management is key to truly Maximizing Your 401(k) in 2026.
Diversifying Your 401(k) Portfolio for Growth
Diversification remains a cornerstone of sound investment strategy, especially within a 401(k). Spreading investments across different asset classes, industries, and geographies can mitigate risk and enhance potential returns.
For 2026, consider re-evaluating your exposure to emerging markets, technology sectors, and sustainable investing options, as these areas may offer compelling growth prospects.
The goal is to create a resilient portfolio that can withstand market fluctuations while capturing upside potential.
Target-date funds, often a default option, automatically adjust their asset allocation as you approach retirement, becoming more conservative over time.
While convenient, it’s crucial to understand their underlying holdings and ensure they align with your individual risk profile and timeline when Maximizing Your 401(k) in 2026.
- Evaluate exposure to different market sectors and global regions.
- Consider the role of target-date funds versus self-managed portfolios.
- Explore options for responsible or sustainable investing if available.
The investment choices within your 401(k) are critical for long-term wealth accumulation. A well-diversified and strategically managed portfolio can significantly amplify the impact of increased contribution limits, securing a more robust retirement.
Employer Contributions and Matching Programs
Employer contributions, particularly matching programs, represent a fundamental component of 401(k) benefits that employees should never overlook. These contributions are essentially free money, significantly boosting your retirement savings.
Many companies offer a dollar-for-dollar match up to a certain percentage of an employee’s salary, or a fifty-cent-on-the-dollar match. Understanding your employer’s specific matching formula is crucial for optimizing your own contributions.
Ensuring you contribute at least enough to receive the full employer match should be a top priority for anyone aiming for Maximizing Your 401(k) in 2026. This immediate return on investment is often unparalleled.
Leveraging Your Employer’s Match
Failing to contribute at least the amount necessary to receive the full employer match is akin to leaving money on the table. This is often cited as one of the biggest financial mistakes employees make.
For 2026, as contribution limits potentially rise, employers may also adjust their matching policies or the thresholds for receiving the full match. It is imperative to review your plan documents or consult with your HR department for the most current information.
Even if you are unable to contribute the maximum allowed, prioritizing contributions up to the employer match ensures you are taking full advantage of this valuable benefit. This strategy is a cornerstone of prudent retirement planning and critical for Maximizing Your 401(k) in 2026.
- Confirm your employer’s 401(k) matching policy for 2026.
- Always contribute at least enough to receive the full match.
- Understand vesting schedules for employer contributions.
Employer contributions provide a powerful accelerant to your retirement savings. These funds grow tax-deferred alongside your own contributions, creating a substantial nest egg over the duration of your career.
Roth 401(k) Considerations for 2026
The Roth 401(k) option continues to gain popularity, offering a distinct advantage for those who anticipate being in a higher tax bracket during retirement. Contributions to a Roth 401(k) are made with after-tax dollars, but qualified withdrawals in retirement are tax-free.
For 2026, as income levels and tax policies evolve, evaluating whether a Roth 401(k) aligns with your long-term tax strategy is more important than ever. This decision depends heavily on your current income, future income projections, and overall financial outlook.
It’s a strategic choice that can significantly impact the tax efficiency of your retirement income. Understanding the nuances between traditional and Roth 401(k)s is key to Maximizing Your 401(k) in 2026.
Traditional vs. Roth: Which is Right for You?
The primary difference lies in when you pay taxes: now with a Roth, or later with a traditional 401(k). A traditional 401(k) offers an immediate tax deduction on contributions, but withdrawals in retirement are taxed as ordinary income.
Conversely, Roth 401(k) contributions do not provide an upfront tax deduction, but qualified distributions in retirement are entirely tax-free.
This can be particularly advantageous for younger workers or those currently in a lower tax bracket who expect their income to grow.
Consider your current income, anticipated income growth, and future tax landscape when making this decision. A financial advisor can help you model different scenarios to determine the most beneficial approach for Maximizing Your 401(k) in 2026.
- Assess your current and projected future tax brackets.
- Understand the implications of pre-tax vs. after-tax contributions.
- Consider the potential for tax-free growth and withdrawals in retirement.
The choice between a traditional and Roth 401(k) is a personal one, with significant long-term implications for your retirement income. It’s a decision that warrants careful consideration and professional guidance.
Navigating Market Volatility and Investment Outlook
The investment landscape leading into 2026 is expected to present both opportunities and challenges, with market volatility remaining a constant consideration.
Investors should maintain a long-term perspective and avoid making rash decisions based on short-term market fluctuations.
Economic forecasts suggest continued global growth, albeit with potential headwinds from inflation and geopolitical events. Diversification and a well-defined investment strategy are essential tools for navigating these complexities.
Regularly rebalancing your 401(k) portfolio to ensure it aligns with your risk tolerance and financial goals is a prudent practice. This proactive approach helps in Maximizing Your 401(k) in 2026.
Strategies for a Resilient 401(k) Portfolio
One effective strategy is dollar-cost averaging, where you invest a fixed amount regularly, regardless of market highs or lows. This approach can smooth out returns over time and reduce the risk of investing a large sum at an unfavorable market peak.
Another key strategy involves understanding the underlying assets of your chosen funds. Knowing whether your funds are heavily weighted in growth stocks, value stocks, or international equities can help you make informed decisions about diversification.
Remaining disciplined and avoiding emotional reactions to market news are paramount. A consistent, long-term approach, coupled with periodic reviews, is crucial for Maximizing Your 401(k) in 2026 and achieving your retirement objectives.
- Implement dollar-cost averaging to mitigate market timing risks.
- Regularly review and rebalance your portfolio to maintain desired asset allocation.
- Stay informed about economic trends but avoid impulsive investment decisions.
Market volatility is an inherent part of investing, but with a well-thought-out strategy and a long-term outlook, your 401(k) can continue to grow effectively. Patience and discipline are your strongest allies.
The Impact of Inflation on Your Retirement Savings
Inflation continues to be a significant factor influencing the real value of retirement savings. While increased contribution limits help, understanding inflation’s erosive effect on purchasing power is critical for long-term financial planning.
For 2026, economists project varying inflation rates, making it essential to factor this into your investment strategy. Ensuring your investments are generating returns that outpace inflation is key to preserving and growing your wealth.
Consider investments that historically perform well during inflationary periods, such as real estate, commodities, or inflation-protected securities. This proactive approach is vital for Maximizing Your 401(k) in 2026.
Protecting Your 401(k) from Inflation
Diversifying your 401(k) to include assets that historically offer some protection against inflation can be a wise move. This might involve exploring funds that invest in real assets or those designed to track inflation.
Another strategy is to ensure your expected retirement income, including Social Security and other pensions, is inflation-adjusted. This helps to maintain your lifestyle and purchasing power throughout your retirement years.
Regularly reviewing your retirement projections with a financial advisor can help you assess whether your savings trajectory is sufficient to counteract the effects of inflation. This vigilance is crucial for Maximizing Your 401(k) in 2026.
While inflation can reduce the purchasing power of your savings, strategic investment choices and careful planning can help mitigate its impact. Staying ahead of economic trends is essential for preserving your financial future.
KanguruNews.com is dedicated to providing timely and accurate financial information to empower our readers. These insights into 401(k) changes for 2026 are designed to help you make informed decisions about your retirement planning.
Future-Proofing Your Retirement Plan
Looking beyond 2026, the landscape of retirement planning will continue to evolve, influenced by legislative changes, economic shifts, and technological advancements. Adopting a flexible and proactive approach is paramount.
Stay informed about potential changes to tax laws, Social Security benefits, and healthcare costs in retirement, as these can significantly impact your financial projections. Continuous education and adaptation are key.
Regularly review your overall financial plan, not just your 401(k), to ensure all components are working in harmony towards your retirement goals. This holistic view is essential for truly Maximizing Your 401(k) in 2026.
Adapting to Legislative and Economic Changes
Legislative changes, such as adjustments to the Secure Act or potential new retirement savings incentives, can create both challenges and opportunities. Staying abreast of these developments allows you to adapt your strategy effectively.
Economic shifts, including interest rate changes and market cycles, also necessitate periodic review of your investment portfolio. What works well in one economic environment may not be optimal in another.
Engaging with financial news and expert analysis can provide valuable insights into these broader trends. This informed approach ensures your retirement plan remains robust and adaptable, contributing to Maximizing Your 401(k) in 2026.
- Monitor legislative changes affecting retirement accounts.
- Adapt investment strategies to changing economic conditions.
- Regularly consult with financial professionals for personalized advice.
Future-proofing your retirement plan involves a commitment to continuous learning and periodic adjustments. The financial world is dynamic, and your plan should be too, ensuring long-term security.
Consulting Financial Professionals for Personalized Advice
While general information on Maximizing Your 401(k) in 2026 is valuable, personalized advice from a qualified financial professional is often indispensable. They can provide tailored strategies based on your unique situation.
A financial advisor can help you navigate complex investment choices, understand the implications of tax laws, and create a comprehensive retirement plan. Their expertise can be crucial in optimizing your savings and investments.
When selecting an advisor, look for credentials such as Certified Financial Planner (CFP) and ensure they operate as a fiduciary, meaning they are legally bound to act in your best interest. This ensures trustworthy and objective guidance.
The Value of Expert Financial Guidance
An expert can help you assess your risk tolerance accurately, which is fundamental to building an appropriate investment portfolio within your 401(k). They can also identify potential blind spots in your current plan.
They can also assist in integrating your 401(k) strategy with other financial goals, such as college savings, homeownership, or estate planning. A holistic approach is always more effective than isolated planning.
Ultimately, a financial professional can provide peace of mind, knowing that your retirement planning is in capable hands and aligned with your long-term aspirations. Their insights are invaluable for Maximizing Your 401(k) in 2026.
Working with a financial professional can significantly enhance your ability to achieve your retirement goals. Their guidance can help you make informed decisions and navigate the complexities of financial planning with confidence.
| Key Point | Brief Description |
|---|---|
| 2026 Limits | Projected increases for standard and catch-up contributions. |
| Investment Strategy | Diversify portfolio, consider market trends and risk tolerance. |
| Employer Match | Maximize free money by contributing up to the full employer match. |
| Roth vs. Traditional | Evaluate tax implications for current and future income brackets. |
Frequently Asked Questions About 401(k) in 2026
What are the expected 401(k) contribution limits for 2026?▼While official figures are pending, financial experts project an increase in both standard and catch-up contribution limits for 2026 due to inflation adjustments. These changes will allow individuals to save more tax-advantaged money for retirement.
How can I maximize my employer’s 401(k) match?▼To maximize your employer’s match, ensure you contribute at least the percentage of your salary required to receive the full company contribution. This is essentially free money and is a critical step in boosting your retirement savings.
Should I choose a Traditional or Roth 401(k) for 2026?▼The choice depends on your current and projected future tax situation. A Traditional 401(k) offers upfront tax deductions, while a Roth 401(k) provides tax-free withdrawals in retirement. Consulting a financial advisor can help you make an informed decision.
What investment strategies should I consider for my 401(k) in 2026?▼Diversification, regular rebalancing, and dollar-cost averaging are key strategies. Consider reviewing your asset allocation to align with market outlooks and your personal risk tolerance, potentially exploring growth or inflation-protected assets.
How does inflation impact my 401(k) savings for 2026?▼Inflation reduces the purchasing power of your future retirement income. It’s crucial to invest in assets that can outpace inflation and to factor its effects into your long-term financial planning to maintain your desired lifestyle in retirement.
Impact and Implications
The anticipated changes to 401(k) contribution limits for 2026, coupled with evolving investment opportunities, underscore the critical need for proactive financial planning.
These adjustments directly empower individuals to enhance their retirement security, provided they are informed and strategic.
KanguruNews.com will continue to monitor official announcements from the IRS and other regulatory bodies, providing timely updates as they become available.
Readers are encouraged to integrate this information into their ongoing financial reviews and discussions with advisors.
Ultimately, Maximizing Your 401(k) in 2026 is not merely about increasing contributions, but about making informed, strategic decisions that align with your long-term financial health and retirement aspirations.