Navigating New Interest Rate Hikes: Mortgage Impact & Adjustments
Anúncios
Latest developments on Navigating the New Interest Rate Hikes: How 3 Recent Adjustments Affect Your Mortgage Payments, with key facts, verified sources, and what readers need to monitor next in Estados Unidos, presented clearly in Inglês (Estados Unidos) (en-US).
Navigating the New Interest Rate Hikes: How 3 Recent Adjustments Affect Your Mortgage Payments is shaping today’s agenda with new details released by officials and industry sources. This update prioritizes what changed, why it matters, and what to watch next, in a straightforward news format.
The Federal Reserve’s recent decisions to increase the benchmark interest rate have sent ripples across the U.S. economy, particularly impacting the housing market. For millions of American homeowners and prospective buyers, these adjustments directly translate into evolving mortgage scenarios.
Understanding the cascade effect of these rate hikes, from central bank policy to your monthly budget, is paramount. This article delves into the specifics of the three most recent adjustments and their tangible implications for mortgage interest rates.
We will examine the immediate and projected long-term consequences, providing context and actionable insights to help you navigate this dynamic financial landscape effectively.
Anúncios
The Federal Reserve, in its ongoing effort to combat inflation, has systematically raised the federal funds rate, influencing borrowing costs across the board. These policy shifts are not isolated events but rather strategic moves designed to cool down an overheating economy.
For consumers, particularly those with mortgages or considering purchasing a home, these decisions translate directly into higher borrowing expenses. It is crucial to grasp the mechanisms through which these adjustments affect various mortgage products.
The current economic climate necessitates a proactive approach to financial planning, especially concerning significant debts like home loans. Staying informed about the Federal Reserve’s actions and their subsequent market effects is the first step in effective financial management.
Understanding the Federal Funds Rate and Mortgage Rates
The federal funds rate is a target rate set by the Federal Open Market Committee (FOMC) for overnight borrowing between banks. While it doesn’t directly dictate mortgage rates, it significantly influences the prime rate and, consequently, other consumer lending rates.
Mortgage rates, particularly for fixed-rate loans, are more closely tied to the yield on U.S. Treasury bonds, which react to expectations of future inflation and economic growth. However, the Fed’s actions create a general upward pressure on all interest rates, including those for mortgages.
Adjustable-rate mortgages (ARMs) are more directly affected by short-term rate changes, as their interest rates reset periodically based on an index tied to the federal funds rate or another benchmark. This direct correlation means ARM holders often feel the immediate pinch of rate hikes.
The First Recent Hike: Initial Market Reactions
The initial rate hike signaled a definitive shift in monetary policy, moving away from the era of ultra-low interest rates. This adjustment immediately triggered a response in the bond market, pushing Treasury yields higher.
Anúncios
Mortgage lenders, anticipating increased borrowing costs for themselves, quickly adjusted their offerings, leading to an uptick in average mortgage rates. This first move served as a wake-up call for many, indicating that the cost of homeownership was set to rise.
Prospective homebuyers faced a sudden increase in their potential monthly payments, prompting many to re-evaluate their budgets and housing affordability. Existing homeowners with ARMs also began to see their payments climb as their rates reset.
- Mortgage rates saw an immediate increase following the announcement.
- Buyer demand showed initial signs of cooling due to higher costs.
- Financial institutions began tightening lending standards slightly.
The Second Hike: Sustained Upward Pressure
The second interest rate hike reinforced the Federal Reserve’s commitment to controlling inflation, sending a clear message to the markets. This sustained pressure on borrowing costs further elevated mortgage rates, making home loans even more expensive.
For many, the cumulative effect of two consecutive hikes started to become more pronounced, impacting affordability and prompting a more cautious approach to real estate. The housing market began to show more noticeable signs of deceleration.
Homeowners with variable-rate mortgages experienced another round of payment increases, necessitating a review of their financial strategies. The sustained upward trend made refinancing less attractive for many fixed-rate mortgage holders.
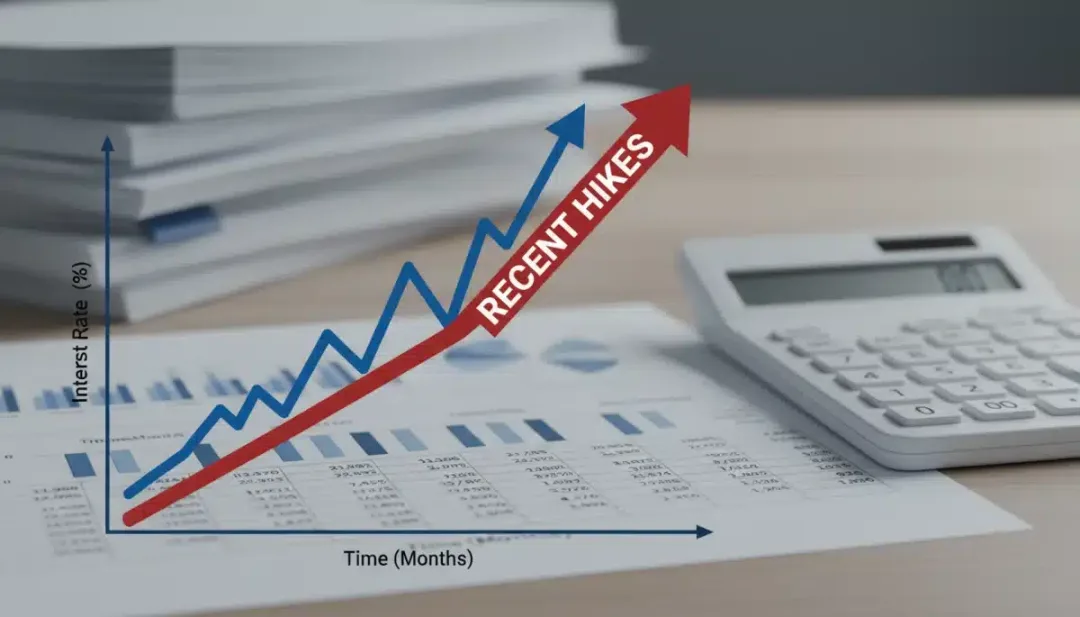
The Third Adjustment: Solidifying the Trend
The most recent interest rate adjustment solidified the trend of rising borrowing costs, underscoring the Federal Reserve’s unwavering focus on price stability. This third hike cemented a new reality for the housing market, where higher mortgage rates are now the norm.
This latest move has further constrained housing affordability, particularly for first-time buyers who rely heavily on competitive interest rates. The market is adapting to this new environment, with some areas experiencing a slowdown in sales volume and price growth.
For current homeowners, especially those with ARMs, the consistent increases mean a continued need to adjust budgets and explore options. The cumulative impact of these three hikes makes Navigating the New Interest Rate Hikes: How 3 Recent Adjustments Affect Your Mortgage Payments a critical concern.
Impact on Fixed-Rate Mortgages
While fixed-rate mortgages are immune to rate changes after origination, the recent hikes significantly impact new borrowers. Those seeking to purchase a home now face substantially higher monthly payments compared to just a few months ago.
This increase in monthly payments can drastically reduce purchasing power, forcing buyers to consider smaller homes or less desirable locations. The dream of homeownership becomes more challenging to achieve under these elevated interest rates.
Existing fixed-rate mortgage holders are largely unaffected in terms of their current payments, but the higher rates make refinancing an existing loan less appealing unless they are looking to tap into equity at a higher rate.
- New fixed-rate mortgages are significantly more expensive.
- Purchasing power for new homebuyers has diminished.
- Refinancing for existing fixed-rate holders is largely uneconomical.
Impact on Adjustable-Rate Mortgages (ARMs)
Adjustable-rate mortgages are directly and immediately affected by the Federal Reserve’s rate hikes. As the underlying index to which ARMs are tied increases, so do the monthly payments for homeowners.
Many homeowners who opted for ARMs during periods of low interest rates are now facing significantly higher payments as their adjustment periods arrive. This can create considerable financial strain, especially for those on tight budgets.
It is crucial for ARM holders to understand their loan terms, including caps on rate increases, and to plan for potential future adjustments. Proactive budgeting and exploring refinancing options, if available, become essential strategies.
Strategies for Homeowners and Buyers
For homeowners with adjustable-rate mortgages, reviewing your current loan terms and understanding future adjustment schedules is paramount. Consider whether refinancing into a fixed-rate mortgage, even at a higher rate than before, might offer more payment stability.
Prospective homebuyers must adjust their expectations and budgeting strategies. This might involve saving a larger down payment, looking for more affordable properties, or extending their home search timeline until rates stabilize or potentially decrease.
Consulting with a financial advisor or mortgage professional can provide personalized guidance tailored to your specific situation. They can help you explore all available options and make informed decisions in this challenging environment.
Refinancing Considerations Amidst Rising Rates
The calculus for refinancing has shifted dramatically with rising interest rates. While a few months ago, many homeowners were refinancing to lower their rates, today the primary motivation might be to switch from an ARM to a fixed-rate loan for payment predictability.
Even if the new fixed rate is higher than your current ARM rate, the stability and certainty of a consistent monthly payment can be invaluable for long-term financial planning. This move can protect you from future rate increases.
However, refinancing involves closing costs and fees, so a thorough cost-benefit analysis is essential. Ensure that the long-term savings or stability outweigh the upfront expenses involved in the refinancing process.
Budgeting and Financial Planning in the New Environment
With mortgage payments potentially increasing, especially for ARM holders, meticulous budgeting becomes more critical than ever. Review your household expenses to identify areas where you can cut back or optimize spending.
Creating an emergency fund can provide a crucial buffer against unexpected financial strains, including sudden increases in mortgage payments. Aim for at least three to six months of living expenses saved.
Exploring additional income streams or making extra payments on your mortgage when possible can help mitigate the impact of rising rates. Proactive financial planning is the key to successfully Navigating the New Interest Rate Hikes: How 3 Recent Adjustments Affect Your Mortgage Payments.
Exploring Loan Modification Programs
If you are struggling to meet your mortgage payments due to rising interest rates, do not hesitate to contact your loan servicer. Many lenders offer loan modification programs designed to help homeowners facing financial hardship.
These programs can involve adjusting your loan terms, such as extending the repayment period, or even temporarily reducing your interest rate. The goal is to make your monthly payments more manageable and prevent foreclosure.
Eligibility for loan modification programs varies, so it is important to communicate openly with your lender and provide all necessary documentation. Seeking assistance early can make a significant difference in preventing more severe financial difficulties.
The Broader Economic Picture and Future Outlook
The Federal Reserve’s actions are part of a larger strategy to bring inflation under control, which is beneficial for the economy in the long run. However, the path to price stability often involves short-term economic adjustments, including higher borrowing costs.
While predicting future interest rate movements is challenging, current indications suggest that the Fed will continue to monitor economic data closely. Any further hikes would be contingent on inflation trends and labor market conditions.
Homeowners and prospective buyers should remain vigilant, keeping an eye on economic indicators and official announcements. The ability to adapt to changing market conditions will be crucial for successfully Navigating the New Interest Rate Hikes: How 3 Recent Adjustments Affect Your Mortgage Payments in the coming months.
Market Responses and Consumer Confidence
The housing market has shown varied responses to the recent rate hikes, with some regions experiencing a slowdown in demand and price appreciation. Consumer confidence in the housing sector has also seen fluctuations.
While higher mortgage rates deter some buyers, others remain active, adapting their strategies to the new financial landscape. The market dynamics are a complex interplay of supply, demand, and affordability constraints.
Understanding these broader market responses can help individuals make more informed decisions about buying, selling, or retaining their properties. It’s not just about personal finances but also about the overall economic environment.
| Key Point | Brief Description |
|---|---|
| Rate Hikes Impact | Federal Reserve’s three recent adjustments directly raise mortgage costs. |
| ARM vs. Fixed | ARMs see immediate payment increases; new fixed-rate loans are more expensive. |
| Financial Strategies | Budgeting, potential refinancing, and seeking professional advice are crucial. |
| Market Outlook | Continued vigilance on Fed policy and economic indicators is essential. |
Frequently Asked Questions About Mortgage Rate Hikes
How do Federal Reserve rate hikes directly affect my mortgage?▼Federal Reserve rate hikes primarily influence mortgage rates by increasing the cost of borrowing for banks. This, in turn, leads to higher interest rates on new fixed-rate mortgages and directly impacts the adjustable rates on existing ARMs as their reset periods occur. The overall cost of homeownership rises significantly.
What should I do if I have an adjustable-rate mortgage (ARM)?▼If you have an ARM, closely monitor your adjustment schedule and understand the caps on your rate increases. Consider contacting your lender to explore options like refinancing into a fixed-rate mortgage, even if the new rate is higher than your initial ARM rate, to secure payment stability. Budgeting for higher payments is also crucial.
Is it still a good time to buy a home with rising mortgage interest rates?▼Buying a home with rising mortgage interest rates requires careful consideration. Affordability decreases as monthly payments increase. It’s essential to reassess your budget, consider a larger down payment, and explore more affordable property options. Consulting a real estate agent and financial advisor can provide tailored insights for your situation.
How can I prepare my finances for potential future mortgage rate increases?▼To prepare for future increases, focus on strengthening your financial position. Build an emergency fund, reduce other debts, and review your budget to identify areas for savings. If possible, consider making extra principal payments on your mortgage to reduce the overall loan amount and interest paid over time.
Will mortgage rates come down again soon?▼Predicting future mortgage rate movements is challenging and depends on various economic factors, including inflation and the Federal Reserve’s policy decisions. While rates could stabilize or decrease in the long term, short-term trends suggest continued vigilance. Stay informed by following economic news and expert analyses to anticipate potential shifts.
What this means
The recent interest rate hikes represent a significant shift in the financial landscape, demanding careful attention from homeowners and prospective buyers. Navigating the New Interest Rate Hikes: How 3 Recent Adjustments Affect Your Mortgage Payments requires a proactive and informed approach to financial planning. Staying abreast of Federal Reserve announcements and understanding their implications for your mortgage is essential. These adjustments underscore the importance of financial resilience and adaptability in a dynamic economy, impacting everything from housing affordability to personal budgeting strategies.