2026 Federal Reserve Interest Rate Hikes: How to Optimize Your Savings and Investment Returns by 1.5%
Anúncios
With the Federal Reserve shifting gears, letting your money sit idle is no longer an option. Now is the perfect time to Optimize Your Savings and position your hard-earned cash to outpace changing economic tides.
Achieving a 1.5% boost on your financial returns might sound ambitious, but tactical adjustments to your capital growth strategy can unlock hidden yields. This quick guide breaks down how to navigate the upcoming interest rate adjustments without the jargon.
From maximizing high-yield accounts to secure wealth accumulation, we explore the exact moves needed to shield and grow your assets. Let’s dive into the data-driven insights that will future-proof your wallet for the year ahead.
Understanding the Federal Reserve’s Role and 2026 Outlook
The Federal Reserve, as the central bank of the United States, plays a critical role in influencing the nation’s economy through its monetary policy decisions, primarily adjusting the federal funds rate.
These adjustments have a ripple effect across all financial markets, impacting everything from consumer loans to investment returns.
Anúncios
Projections for 2026 suggest a period of continued vigilance from the Fed, potentially leading to further interest rate hikes aimed at managing inflation and ensuring economic stability.
This forward-looking perspective is crucial for individuals who wish to proactively manage their financial assets.
For those focused on Optimize Your Savings, understanding these underlying economic forces is the first step toward strategic financial maneuvering. Being informed allows for timely adjustments rather than reactive measures.
The Mechanism of Rate Hikes and Your Money
When the Federal Reserve raises interest rates, it typically makes borrowing more expensive for banks, which in turn passes those costs onto consumers and businesses. This impacts mortgage rates, credit card APRs, and the interest earned on savings accounts.
However, higher rates also mean better returns on certain fixed-income investments and savings products.
Identifying these opportunities early is key to optimizing your financial position. It’s about shifting from low-yield options to those that benefit from the new rate environment.
The interconnectedness of these financial elements requires a holistic view. A slight increase in interest rates can significantly alter the attractiveness of different asset classes, demanding a re-evaluation of current financial strategies.
Anúncios
Why 2026 is a Pivotal Year
The year 2026 is anticipated to be pivotal due to the potential culmination of several economic trends, including inflation management and the Fed’s ongoing efforts to normalize monetary policy. This makes it a critical juncture for personal finance planning.
Economic forecasts suggest that the cumulative effect of rate adjustments could become more pronounced, creating a definitive landscape for savers and investors. Preparing now ensures that you are positioned to capitalize on these shifts, rather than being caught off guard.
Therefore, proactive engagement with financial planning, specifically tailored to the 2026 outlook, is not merely advisable but essential for anyone aiming to enhance their financial standing. This foresight is what separates informed investors from the rest.
Strategies for Optimizing Savings Accounts
As interest rates rise, traditional savings accounts, money market accounts, and certificates of deposit (CDs) become more attractive. It is imperative to review your current savings vehicles and consider alternatives that offer higher yields in this evolving environment.
Many financial institutions offer competitive rates on high-yield savings accounts, which can significantly boost your returns without taking on additional risk. These accounts are often FDIC-insured, providing peace of mind alongside increased earnings.
The objective is to ensure that every dollar in your savings is working as hard as possible. This means actively seeking out the best available rates and being willing to move funds to more lucrative options to maximize your returns.
High-Yield Savings Accounts (HYSAs)
High-Yield Savings Accounts (HYSAs) are often the first line of defense for individuals looking to increase their savings returns during periods of rising interest rates.
These accounts typically offer significantly higher interest rates than traditional savings accounts, often from online banks.
The key advantage of HYSAs is their liquidity, allowing you to access your funds relatively easily while still earning a competitive rate. This makes them ideal for emergency funds or short-term savings goals where capital preservation and growth are equally important.
To truly optimize savings returns, regularly compare HYSA offerings from various banks. Rates can fluctuate, and staying informed about the best available options ensures you are always maximizing your interest earnings.
- Research and compare HYSA rates from different online and traditional banks.
- Consider accounts with no monthly fees and low minimum balance requirements.
- Ensure the bank is FDIC-insured for protection of your deposits.
- Set up automatic transfers to consistently contribute to your high-yield savings.
Certificates of Deposit (CDs)
Certificates of Deposit (CDs) offer a more structured approach to saving, providing fixed interest rates for a specified term. As interest rates climb, longer-term CDs can lock in higher yields, protecting your returns from potential future rate drops.
A CD laddering strategy, where you invest in CDs of varying maturities, can provide both flexibility and access to funds while still benefiting from higher rates. This approach allows you to reinvest maturing CDs at potentially even higher rates.
For those focused on Optimize Your Savings, CDs can be a powerful tool for conservative growth. They offer predictability and security, especially when rates are on an upward trend.
- Explore different CD terms, from short-term to long-term, based on your financial goals.
- Consider a CD ladder strategy to balance liquidity and higher yields.
- Compare early withdrawal penalties across different institutions before committing.
- Look for promotional CD rates that may offer an additional boost to your returns.
Enhancing Investment Returns Through Strategic Allocation
Beyond traditional savings, optimizing your investment portfolio is crucial for achieving a 1.5% increase in returns during a period of rising interest rates. This often involves re-evaluating asset allocation and identifying sectors that historically perform well in such environments.
Fixed-income investments, particularly short-to-medium term bonds, can become more attractive as their yields rise. However, it’s essential to understand the inverse relationship between bond prices and interest rates, which dictates careful selection.
Equity markets can also present opportunities, though certain sectors may be more resilient or even thrive amidst higher rates. A diversified approach remains key, but with a nuanced understanding of how different asset classes react.
Re-evaluating Your Bond Portfolio
Rising interest rates generally lead to a decrease in the value of existing bonds, especially those with longer maturities. Therefore, adjusting your bond portfolio to favor shorter-duration bonds can help mitigate interest rate risk.
Short-term bonds and bond funds tend to be less sensitive to interest rate fluctuations, making them a safer bet in a rising rate environment. They also mature sooner, allowing you to reinvest at potentially higher rates.
For those aiming to optimize savings returns, consider Treasury Inflation-Protected Securities (TIPS) as well. These bonds adjust with inflation, providing a hedge against purchasing power erosion, which is often a concern when rates are rising.
Equity Market Considerations
While rising interest rates can sometimes dampen equity market performance, certain sectors tend to be more resilient or even benefit. Financial institutions, for example, often see increased profitability as their lending margins expand.
Companies with strong balance sheets, consistent cash flows, and pricing power are generally better positioned to weather higher borrowing costs. These businesses can pass on increased costs to consumers without significantly impacting demand.
Focus on sectors such as banking, insurance, and utilities, which historically show resilience or growth during periods of rising rates. Diversification across these sectors, rather than concentrating on a single one, is a prudent strategy.
Exploring Alternative Investments and Diversification
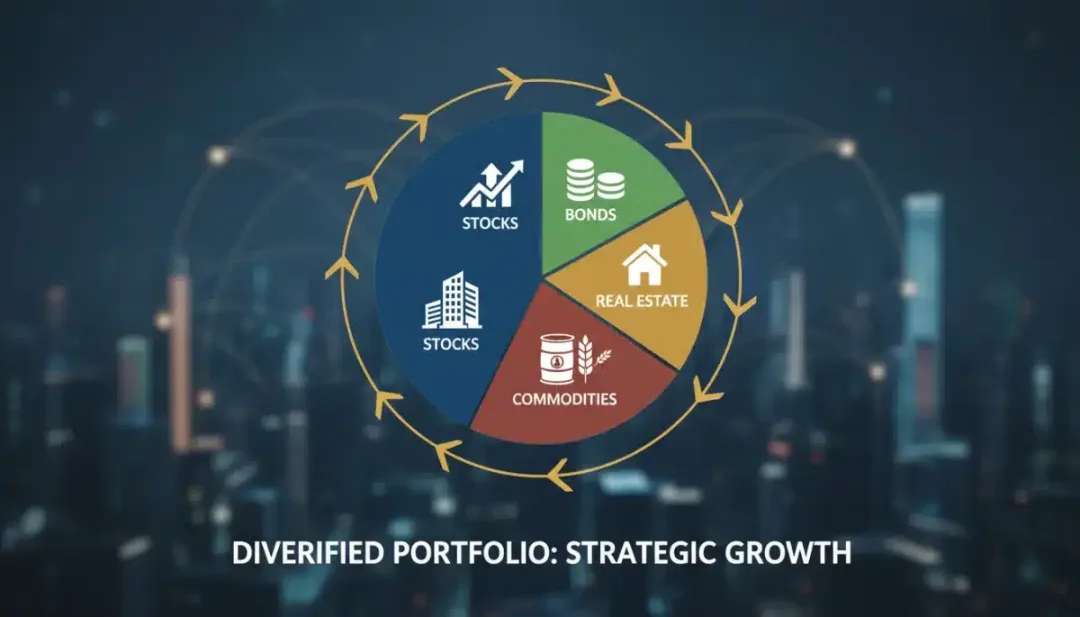
To truly optimize savings returns and achieve that 1.5% increase, broadening your investment horizon beyond traditional stocks and bonds might be necessary.
Alternative investments can offer diversification and unique return profiles that are less correlated with conventional markets.
These alternatives can include real estate, commodities, or even private equity, each carrying its own set of risks and rewards. The key is to carefully assess how these assets perform during periods of rising interest rates and integrate them strategically into your portfolio.
Moreover, diversification remains a cornerstone of any robust investment strategy. Spreading your investments across various asset classes, industries, and geographies can help cushion your portfolio against volatility and unexpected market shifts.
Real Estate Investment Trusts (REITs)
Real Estate Investment Trusts (REITs) can offer an avenue to invest in real estate without directly owning physical property. They often provide steady income streams through dividends, which can be attractive in a rising rate environment.
While REITs can be sensitive to interest rate changes, certain types, like those focused on essential services or data centers, may show more resilience. Their income-generating nature can also offer a hedge against inflation.
It’s important to research the underlying properties and management quality of REITs before investing. A well-chosen REIT can contribute significantly to your goal of Optimize Your Savings.
Commodities and Precious Metals
Commodities, such as oil, natural gas, and agricultural products, can act as an inflation hedge. As the cost of living rises, the value of these raw materials often increases, providing a potential buffer for your portfolio.
Precious metals like gold and silver have historically been considered safe-haven assets during economic uncertainty and periods of high inflation. They tend to hold their value when traditional currencies or equities falter.
Including a small allocation to commodities or precious metals can enhance diversification and potentially boost returns when other asset classes are under pressure. This strategic inclusion plays a role in optimizing your overall financial strategy.
Leveraging Technology for Enhanced Financial Decisions
In today’s fast-paced financial world, technology offers powerful tools to help individuals monitor their investments, identify opportunities, and make informed decisions.
Utilizing financial apps, robo-advisors, and data analytics platforms can significantly streamline your efforts to optimize savings returns.
These digital resources provide real-time market data, personalized financial insights, and automated investment management, often at a lower cost than traditional financial advisors. They empower you to take a more active and informed role in your financial planning.
Embracing technology is not just about convenience; it’s about gaining an edge. It allows for quicker responses to market changes and more precise adjustments to your portfolio, directly contributing to the goal of Optimize Your Savings.
Robo-Advisors and Automated Investing
Robo-advisors utilize algorithms to provide automated, diversified investment management at a fraction of the cost of human financial advisors. They can automatically rebalance your portfolio and invest according to your risk tolerance and financial goals.
For those looking to optimize savings returns without dedicating extensive time to market research, robo-advisors offer a practical solution. They ensure your investments remain aligned with your objectives, even as market conditions shift.
Many platforms also offer tax-loss harvesting and seamless integration with other financial accounts, further enhancing their value. This automated approach can be particularly beneficial during volatile periods, helping maintain discipline.
Financial Tracking and Analytical Tools
A plethora of financial tracking apps and analytical tools are available to help you monitor your spending, track your investments, and analyze your portfolio’s performance. These tools provide a clear overview of your financial health.
By aggregating all your financial accounts in one place, these platforms enable you to identify areas where you can save more, invest more efficiently, or reallocate funds for better returns. They provide the data needed for informed decisions.
Regularly reviewing your financial dashboard can highlight opportunities for improvement, such as optimizing savings returns by moving idle cash to a high-yield account or identifying underperforming investments that need adjustment.
Proactive Debt Management in a Rising Rate Environment
While the focus is often on optimizing savings and investment returns, effective debt management becomes equally critical when interest rates are on the rise. High-interest debt can quickly erode any gains made through strategic investments.
Prioritizing the repayment of variable-rate debts, such as credit card balances and certain lines of credit, can save you significant amounts in interest payments. These debts become more expensive as the Fed raises rates, directly impacting your disposable income.
Consolidating or refinancing fixed-rate debts before further rate hikes can also lock in lower interest payments, providing financial stability. This proactive approach is an integral part of Optimize Your Savings.
Tackling High-Interest Variable Debt
Credit card debt and personal loans with variable interest rates are particularly vulnerable to rising Federal Reserve rates. As the federal funds rate increases, the interest rates on these debts will likely follow suit, making them more expensive to carry.
Prioritizing the repayment of these high-interest variable debts should be a top financial goal. Strategies like the debt snowball or debt avalanche method can provide a structured approach to eliminating these burdens, freeing up capital for investment.
Reducing these liabilities not only saves you money on interest but also improves your overall financial health, providing more flexibility to invest in opportunities that arise from the changing rate environment. This is a crucial step to optimize savings returns.
Evaluating Mortgage and Loan Refinancing
For homeowners, assessing your mortgage situation is vital. If you have an adjustable-rate mortgage (ARM), rising interest rates could lead to higher monthly payments. Converting to a fixed-rate mortgage before significant hikes could provide stability.
Even with fixed-rate mortgages, exploring refinancing options might be beneficial if you can secure a lower rate or a shorter term, especially if your current rate is higher than what’s available. However, this decision should consider closing costs and your long-term plans.
Similarly, for other fixed-rate loans like auto loans or student loans, reviewing the terms and considering refinancing at a lower rate, if available, can free up cash flow. This proactive debt management contributes directly to your ability to optimize savings returns.
Long-Term Financial Planning and Professional Guidance
Achieving and sustaining a 1.5% optimization in your savings and investment returns amidst Federal Reserve rate hikes requires a long-term perspective and disciplined financial planning. This isn’t a one-time adjustment but an ongoing process that adapts to economic shifts.
Regularly reviewing your financial plan, setting clear goals, and making incremental adjustments are essential. This continuous engagement ensures that your strategy remains relevant and effective as market conditions evolve over time.
While many resources are available for self-management, seeking professional financial guidance can provide invaluable expertise and personalized strategies. A qualified advisor can help you navigate complex decisions and ensure you are on track to meet your financial objectives.
Setting Realistic Financial Goals
Clearly defined, realistic financial goals are the bedrock of any successful long-term financial plan. Whether it’s saving for retirement, a down payment, or a child’s education, specific goals provide direction and motivation.
When interest rates are rising, it’s particularly important to revisit these goals and adjust your savings and investment contributions accordingly. Higher returns on certain instruments can accelerate your progress, while increased debt costs might require re-prioritization.
For those focused on Optimize Your Savings, integrating this target into your broader financial goals ensures a cohesive and achievable plan. Regular progress checks are vital.
The Value of a Financial Advisor
While DIY investing is increasingly popular, the complexity of a rising interest rate environment often warrants the expertise of a seasoned financial advisor. They can provide tailored advice, risk assessment, and help construct a diversified portfolio.
A good advisor can help you understand the nuances of various investment vehicles, identify tax-efficient strategies, and ensure your portfolio is aligned with your long-term objectives. Their objective perspective can be particularly valuable during market volatility.
For individuals committed to optimizing savings returns, a financial advisor can be a strategic partner, offering guidance that goes beyond general advice. They help you craft a plan that specifically addresses your unique financial situation and goals.
Monitoring Economic Indicators and Staying Informed
Staying informed about key economic indicators and Federal Reserve communications is paramount for making timely and effective financial decisions.
The economic landscape is dynamic, and being aware of changes can provide a significant advantage in optimizing your savings and investments.
Regularly monitoring inflation rates, employment data, GDP growth, and the Fed’s public statements can offer clues about future monetary policy directions. This foresight allows you to anticipate market shifts rather than reacting to them.
KanguruNews.com provides up-to-date reporting and analysis on these critical economic developments, empowering you to stay one step ahead. Accessing reliable, timely information is a cornerstone of successfully Optimize Your Savings.
Key Economic Indicators to Watch
Several economic indicators provide insights into the health of the economy and potential future actions by the Federal Reserve. Consumer Price Index (CPI) and Personal Consumption Expenditures (PCE) are crucial for understanding inflation trends.
Employment data, including the unemployment rate and non-farm payrolls, offers a snapshot of the labor market, which heavily influences the Fed’s decisions. Strong employment often signals a robust economy, potentially leading to rate hikes.
Gross Domestic Product (GDP) growth indicates the overall economic output. A healthy GDP might give the Fed more room to raise rates without fear of tipping the economy into recession. Monitoring these helps optimize savings returns.
Federal Reserve Communications
The Federal Reserve’s official statements, meeting minutes, and speeches by its members are invaluable sources of information. These communications often signal the Fed’s future intentions regarding interest rates and monetary policy.
Paying close attention to the language used and any shifts in tone can provide early warnings of policy changes. The Fed aims for transparency, making its communications a critical resource for investors and savers.
Understanding the Fed’s dual mandate, maintaining maximum employment and stable prices, helps interpret their actions. This knowledge is essential for effective financial planning and Optimize Your Savings.
| Key Strategy | Actionable Step |
|---|---|
| Optimize Savings Accounts | Transfer funds to high-yield savings accounts and consider CD laddering. |
| Strategic Investment Allocation | Favor short-duration bonds and resilient equity sectors like financials. |
| Diversify with Alternatives | Explore REITs, commodities, and precious metals for inflation hedging. |
| Proactive Debt Management | Prioritize high-interest variable debt repayment and evaluate refinancing. |
Frequently Asked Questions About 2026 Fed Rate Hikes
How will Federal Reserve rate hikes in 2026 impact my savings?▼Higher Federal Reserve rates generally lead to increased interest earnings on savings accounts, particularly high-yield savings accounts and Certificates of Deposit. It’s crucial to actively seek out and move funds to accounts offering the most competitive rates to optimize your savings returns.
What investment strategies are best for navigating rising interest rates?▼Consider adjusting your bond portfolio towards shorter-duration bonds and exploring equity sectors that traditionally perform well in rising rate environments, such as financials. Diversifying with alternative assets like REITs or commodities can also provide a hedge and enhance returns.
Can I really optimize my returns by 1.5% due to rate hikes?▼By strategically reallocating funds to higher-yielding savings products and making informed investment choices, a 1.5% optimization is an achievable goal. This involves proactive management of both savings and investment portfolios, leveraging the new interest rate landscape.
How does debt management factor into optimizing returns?▼Effectively managing debt, especially high-interest variable-rate debt, is critical. Reducing these liabilities frees up capital that can then be invested at higher rates, indirectly contributing to your overall return optimization. Refinancing fixed-rate loans before further hikes can also be beneficial.
Where can I find reliable information to stay informed?▼Staying informed involves monitoring official Federal Reserve communications, key economic indicators like inflation and employment data, and reputable financial news sources. KanguruNews.com offers current, verified information to help you make informed financial decisions and optimize savings returns.
Impact and Implications
The impending Federal Reserve interest rate hikes in 2026 are not merely a headline but a significant financial event requiring careful consideration. Optimize Your Savings demands a proactive and informed approach, spanning both savings and investment strategies.
The insights provided aim to empower individuals to make strategic adjustments, ensuring their financial health thrives in the evolving economic climate. Continuous monitoring of economic data and expert analysis will be key to adapting these strategies effectively.